Self-Storage Financing in 2026: From SBA Stacking to the Earnest Money Gap
Steady demand, rebounding property values, and limited supply: there are plenty of reasons why more operators and investors are looking at self-storage financing this year.
If you’re also looking into self-storage loans, you’re probably excited by this opportunity but unable to move forward because of:
- No upfront capital to buy a self-storage business or build facilities
- Not knowing which self-storage loan options are available or which fit you best
- Too little liquidity to post the deposit necessary to win competitive CRE deals.
Jump these hurdles and chances are you still can’t close on the opportunity. Because while the seller wants to see their deposit in days, your SBA lender’s closing date lands weeks after that.
Most self-storage financing plans don’t account for that funding gap. That’s why this guide covers both self-storage loans and how to get the financing timing right, so that you aren’t held back by a slow lender or a large earnest money deposit.
We’ll cover:
- What SBA loan options exist for self-storage facilities?
- How do stacked SBA loans work as self-storage financing?
- Bridge loans and conventional financing for time-sensitive acquisitions
- How to buy a self-storage facility with no money down
- Cover the deposit before self-storage financing closes with Duckfund
Want to close on a self-storage unit with a convincing early money deposit? Contact Duckfund to find out how you can move fast and efficiently on CRE opportunities.
Fund your next real estate deal
- Access fast financing
- Grow your real estate portfolio
What SBA loan options exist for self-storage facilities?
For owner-operators, loans from the Small Business Administration (SBA) are the first port of call.
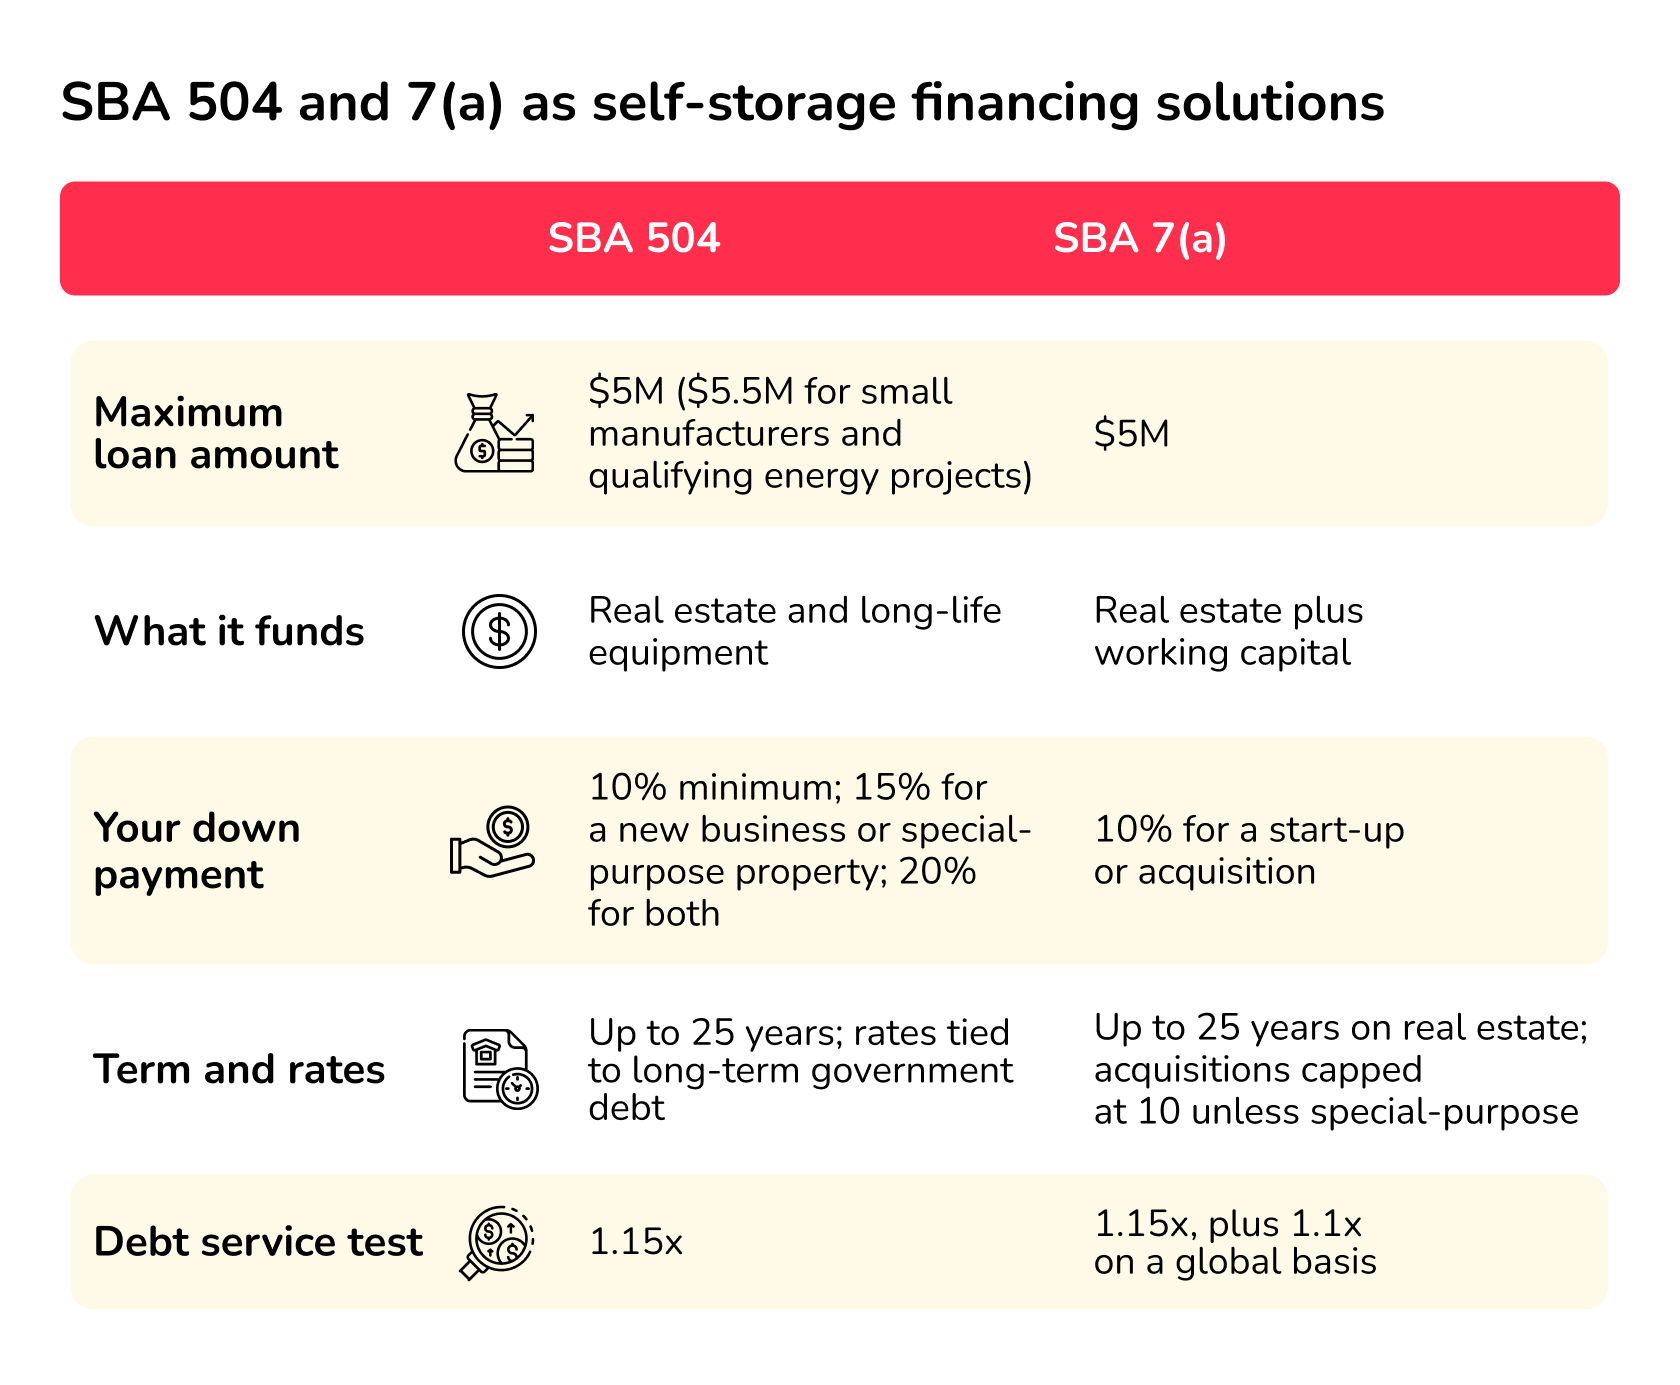
Both SBA programs for real estate allow repayment terms of up to 25 years and down payments of as little as 10%, and they're available for self-storage facilities because SBA treats them as operating businesses.
SBA 504 loans follow a 50/40/10 split. This is where a bank lends at least 50%, and a certified development company (CDC) lends up to 40% through an SBA-backed debenture. You then fund the remaining 10%.
Your contribution rises to 15% if the deal involves either a new business or a limited or special-purpose property. It rises to at least 20% if both apply.
The CDC decides whether a self-storage facility is a limited or special-purpose property, so you should confirm the required equity contribution before you make an offer.
An SBA 7(a) loan works differently. Instead of combining a bank loan and a CDC debenture, one SBA lender makes the loan and SBA guarantees part of it. And while a 504 covers only fixed assets, the SBA 7(a) loan can fund a business acquisition, real estate, equipment, business debt refinancing, and working capital, including eligible lines of credit.
The programs are built for self-storage operators. If you mainly lease out the real estate, or hand a manager full control of day-to-day operations, you're ineligible.
Here is how SBA loan terms compare for self-storage financing.
A quick note on underwriting: the SBA now underwrites purchases based on the facility’s cash flow history instead of projections, as of October 2026. If you’re a first-time buyer, you’ll need 1.25x debt service coverage, so your first lender will need to see at least two years of financials.
Finally, an important catch for SBA 504 loans: they require one job created or retained per $95,000 guaranteed, unless they qualify through another economic-development or public-policy objective. Self-storage facilities can run with lean teams, so it’s worth asking your CDC how the job-creation requirement affects your potential loan amount.
How do stacked SBA loans work as self-storage financing?
The SBA is a viable lending option for self-storage investors but, until this year, came with a ceiling limit of $5 million.
"SBA's loan limits had not been raised for more than a decade, creating a gap in funding for growing small businesses," says SBA Administrator Kelly Loeffler.
This gap could be about to narrow. As of July 2026, the SBA now lets eligible borrowers pair an SBA 7(a) and an SBA 504 loan for a combined loan amount of up to $10M, which is double the earlier cumulative limit of $5M. That opens up SBAs to larger acquisitions and new construction.
That means you can use a 504 for the self-storage property purchase and a 7(a) for working capital, lease-up costs, or expansion.
Here’s how stacking works structurally: the 7(a) goes first. Your lender must flag the companion 504 so SBA processes them in that order, and sequencing around that step is what tends to cause delays.
If you're planning a stacked deal, raise it with your self-storage lender before your letter of intent. Taylor Franco, Senior Vice President and Head of SBA Large Dollar Originations at Regions Bank, advises: “It's important to check with your SBA lender to see how to structure your business and lending now and in the future.”
Yet even a $10M SBA package doesn't solve a time-sensitive acquisition. If the seller wants to see earnest money deposited before your SBA loan closes, you will need another source of funding to keep the deal moving.
Bridge loans and conventional financing for time-sensitive acquisitions
In competitive self-storage markets, buyers are on the clock.
Sellers expect to close far faster than SBA can disburse, which can take up to 90 days from applying to funding. A 504 can even take up to six months. That’s why buyers turn to other commercial real estate loans for gap funding.
A bridge loan is short-term debt secured by the property, used to lock in the deal while permanent financing is arranged or a new facility leases up.
If a bridge loan isn't available in time, hard money loans are a buyer’s last resort. Underwritten mainly on the asset (rather than a credit score), hard money can fund fast but at higher interest rates and origination fees than traditional loans.
The permanent loan can be an SBA loan or conventional storage-unit financing from a bank or credit union. Banks work under the interagency guidelines for real estate lending, which state that a bank's internal loan-to-value (LTV) limits can't exceed 85% for improved property or 80% for commercial construction loans, though exceptions are possible.
Some lenders also offer DSCR loans, which qualify the deal mainly on the property's net operating income rather than your personal income. These loans still carry an LTV limit.
Combining SBA and bank loans for self-storage financing
The two routes ( SBA loans and bank loans) can and often work in tandem. SBA lets a 504 refinance short-term bridge financing of three years or less that paid for eligible project costs, so a bridge can carry you to an SBA closing.
Make sure to check the loan terms before you sign, because a short amortization period, a prepayment penalty, or a strict appraisal can undo the plan.
How to buy a self-storage facility with no money down
New owners can't buy an existing facility with zero capital, but the right mini-storage financing structure can get you very close.
Under SBA's SOP 50 10 8.1, a 7(a) loan for an initial acquisition (a new owner buying a business) requires an equity injection of at least 10% of the purchase price that the lender can't reduce or waive.
An existing operator buying another facility has more options when it comes to working out how to buy commercial property with no money down. The lender may reduce or remove the requirement if the business has enough liquidity and working capital, and no negative net worth, to run the facility afterward.
Yet even if you owe that 10%, it doesn’t have to all be your cash. Cash that isn't borrowed counts in full, including gifted cash. Seller debt on full standby, meaning no payments for the duration of the SBA loan, and money from a passive investor (holding under 20%) can combine to cover up to half the requirement.
On an SBA 504 loan, you can borrow the contribution of 10% or more, as long as that loan sits behind the bank loan and the SBA debenture. If you already own the land, that equity can count toward it too.
However, none of this covers the earnest money deposit, which sellers want within days of signing the purchase and sale agreement, and long before the SBA loan closes.
EMD lending fills that gap. It funds the deposit into escrow without replacing your equity injection.
Cover the deposit before self-storage financing closes with Duckfund
Self-storage financing tends to be slow, but your deposit deadline isn’t. Your SBA or bank loan disburses on the lender's schedule, long after your earnest money deposit is due.
That's why buyers who can't wait on lender approvals look to deposit financing. “EMD financing allows sponsors to confidently make offers”, says Matt Morgan, a licensed CRE agent at Inland Pacific Advisors who has worked on acquisitions since 2008. “This way, they can secure properties ahead of slower, traditional financing approvals.”
Duckfund's soft deposit financing is a leading example. We help you post a strong EMD before the competition by approving deposits in 24 hours and funding them within 48 hours.
We require no collateral, and the deposit is refundable if you exit the deal during the contingency period. We also structure fees as LP soft costs, passed through at closing, with competitive rates that decrease for larger deposits. Just apply before signing the PSA, and we’ll do the rest.
After helping investors acquire over $1.5 billion in acquisitions at a 65% client retention rate, Duckfund has become the acquisition partner that sponsors build their deal pipeline around.
Whether you finance with an SBA loan, a bridge loan, or both, a financed deposit lets you make a competitive offer now while the loan moves through approval.
Closing self-storage financing takes time. Posting the deposit shouldn’t. Apply for EMD financing with Duckfund and get funded 24 hours after approval.
Frequently Asked Questions
1. How do you buy a self-storage facility?
Start down the storage-unit financing route: an SBA 7(a) or 504 loan if you will run the facility, or a bridge or conventional loan if you won't. Plan on equity (typically 10% for an SBA acquisition), order the appraisal, and cover the earnest money deposit before the lender closes.
2. How much does it cost to build a self-storage facility?
Expect construction costs of about $50-85 per square foot for single-story drive-up storage and around $105-140 per square foot for multi-story climate-controlled facilities, according to industry benchmarks. Design, height, and climate control drive most of the difference.
3. What self-storage business loans can investors use if they don't qualify for SBA?
Conventional bank loans, DSCR loans, and CMBS loans are the usual routes, and CMBS loans are typically non-recourse. Lenders underwrite them mainly on the property's income and LTV. A bridge loan can hold the deal until one of them closes.
4. Can an SBA loan for self-storage cover working capital?
Yes. A 7(a) loan can fund working capital alongside real estate, while a 504 funds fixed assets only. Revolving lines of credit are available only through specific SBA programs, such as SBA Express loans of up to $500,000.
5. What is earnest money financing?
Earnest money financing is short-term funding that pays your deposit into escrow so your own cash stays free. With Duckfund, applications are approved within 24 hours, deposits are funded within 48 hours, and the deposit is refundable if you exit during the contingency period.
Real Estate
Financing
- Approval within 24 hours
- Fund multiple properties at once
- No full deposit upfront — soft deposit only
- Apply in under 2 minutes
Secure your next commercial property acquisition — zero upfront capital required.
Start with Duckfund’s EMD financing program.- No capital commitment
- Close faster
- Scale with confidence